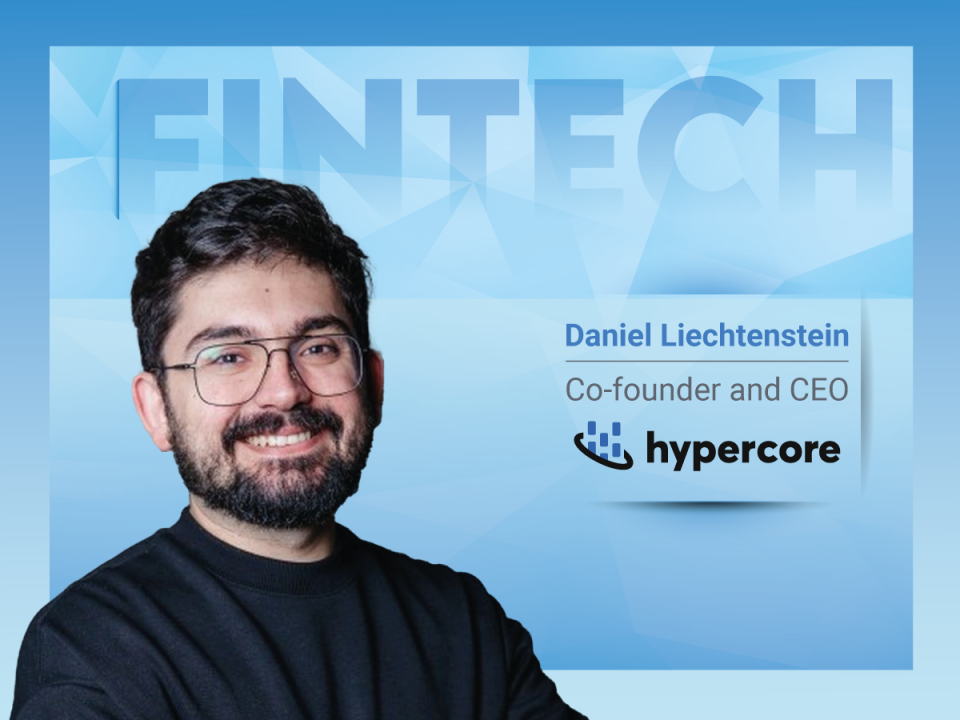
What’s reshaping fund operations in an AI driven era for institutions? Daniel Liechtenstein, co-founder and CEO, Hypercore weighs in with some observations and AI optimization tips:
__________
Why is retail investor participation changing the operational requirements of private credit firms?
Private credit was built for a relatively small number of institutional investors and the operating model reflects that. People could be filling manually the gaps between systems because the volume was manageable.
Retail changes that pretty quickly when you have more investors, more frequent reporting, potentially more liquidity events, and much less room for information to be late or inconsistent. But the assets you are managing are still private credit assets. The loans are bespoke, the documentation is bespoke, there are amendments, different payment structures, covenants, pricing grids. So it’s basically the same operational complexity with a larger investor base to report to.
So you end up with this mismatch where the front end of the market is becoming much more scalable, but the infrastructure underneath it was never really designed for that scale. You cannot solve that indefinitely by adding more people to operations. At some point the underlying model has to change.
How are increased transparency and reporting expectations reshaping fund operations?
For years, private credit firms have been able to live with infrastructure that everyone knows is not ideal (to say the least), but it can work, and replacing core infrastructure is painful, so it keeps going.
What is changing now is that the tolerance for that is getting much lower. First, when you report once a quarter to a small number of institutions, you can spend a lot of time getting the numbers into shape before they go out. That is obviously not the case when information demands are much more frequent. Also, the level of information requested is also deepend. It is not only “what did the fund return?” It is: how much of the interest is cash, how much is PIK, did the borrower’s pricing change, was there an amendment, what happened to leverage, why did this number move?
Those answers all come from the loan level. If every answer requires somebody to reconstruct the history from documents, spreadsheets and different systems, the operating model eventually becomes the constraint. I actually think this is one of the things that will finally push the industry to modernize. People have complained about these processes forever. Complaining was never enough of a reason to replace them, rather having to support a very different level of transparency probably is.
Read More on Fintech : Global Fintech Interview with Baran Ozkan, co-founder & CEO of Flagright
What infrastructure will firms need to scale while maintaining governance and investor confidence?
It might sound almost too obvious but the starting point is having one place where you actually know what the loan looks like. When data lives across different sources (accounting team, administrators, spreadsheets) whether it’s because the internal system are not robust enough or the service providers are not reliable enough, you cannot really automate around that.
So the way I see it, before anything else, you need an authoritative loan record: the current terms, balances, schedules, amendments, what changed, when it changed and the history behind it. Then the other parts of the operating stack can consume that information rather than each rebuilding their own version and that’s how you also get full governance.
And this becomes even more important with AI. There is a lot of excitement now about agents working across the tech stack, and I think that is absolutely where this goes. But funds need to understand first that an agent connected to five inconsistent versions of the same loan is not intelligence but rather the opposite of it.
So the system of record comes first. Then you can do much more interesting things on top of it.
What role will AI and workflow automation play in supporting the next generation of private credit operations?
I think we are still aiming too low with AI.
A lot of the conversation is about whether it can read a document faster, summarize an agreement or save someone twenty minutes. Of course it can, and that is useful. But if that is all we use it for, we are basically applying new technology to the same old operating model.
The bigger opportunity is to take entire workflows that today depend on people moving information from one place to another and rethink them. In private credit operations that might look like something changes in a loan, someone has to understand what happened, figure out what it means under the agreement, update the system, tell the administrator, make sure accounting reflects it and then check that everything ties out. So many workflows that are being handled manually by humans not because they necessarily require judgement but because the systems can’t do it themselves.
That is exactly where AI can make a much bigger difference because if the underlying loan data is reliable, you can have AI understand what happened, apply the relevant terms, trigger the
right workflow, update the systems involved and only bring a person in when there is an exception or a decision that actually needs judgment.
I don’t think that will make private credit become fully autonomous anytime soon, nor should it. But it will definitely break the economic equation of a scaling portfolio – requires more people to support it.
Catch more Fintech Insights : Real-Time Payments and the Redefinition Of Global Liquidity
[To share your insights with us, please write to psen@itechseries.com ]

Hypercore provides an all-in-one platform for non-bank lenders.
Daniel Liechtenstein is the co-founder and CEO of Hypercore, a pioneering company that offers a data-first loan management platform for non-bank commercial lenders. Hypercore’s mission is to simplify and streamline the management of loans, funding, and client data. As a serial entrepreneur, Daniel has extensive experience leading Fintech ventures and software development projects, including core banking systems and open banking APIs. His expertise lies at the intersection of finance and technology, where he consistently drives innovation and efficiency. Daniel holds an MSc in Financial Mathematics and a BA in Economics and Business Management.